
 Français
The acquisition process can be greatly simplified… but that is often undesirable.
A transfer of shares is most often a sale. As such, for the transfer to be legally binding – meaning to effect a transfer of ownership of the shares – there must be an agreement between the parties on two points: the object of the sale, meaning the shares being sold, and the price of the shares.
This agreement, which is the core of the share purchase agreement, is therefore the only necessary stage for a valid transfer of shares to occur. The acquisition process can thus be extremely simple. In our diagram, this refers to the stages 5 and 8 being respectively the execution of the share purchase agreement and the closing which is the completion of the sale.
However, the sale of shares of a company is a specific operation, in the sense that, from a strictly legal point of view, the buyer is purchasing shares, but doing so with consideration for the company whose shares are being transferred. That includes the company’s assets and liabilities, its activities, its employees, its clients, …
The complexity of this object – the company in question – may necessitate that the transfer process contains several stages both preceding and following the execution of the share purchase agreement. These stages are intended to provide the buyer with assurance regarding the qualities of the company whose shares he is about to purchase. They may include sending a letter of intent and the prospective buyer conducting due diligence. These stages are hereafter detailed.
The unique nature of the object the parties are considering also justifies taking special care in the negotiations and the drafting of the share purchase agreement. The share purchase agreement is often a lengthy document, for the simple reason that the transaction is complex.
In conclusion, a transfer of shares can be a very simple transaction, but in many cases, this simplicity is unsatisfactory for the buyer and therefore undesirable.
Stages of the acquisition process
Although there are no rules, just good practice, a typical acquisition process includes the stages shown in this diagram.
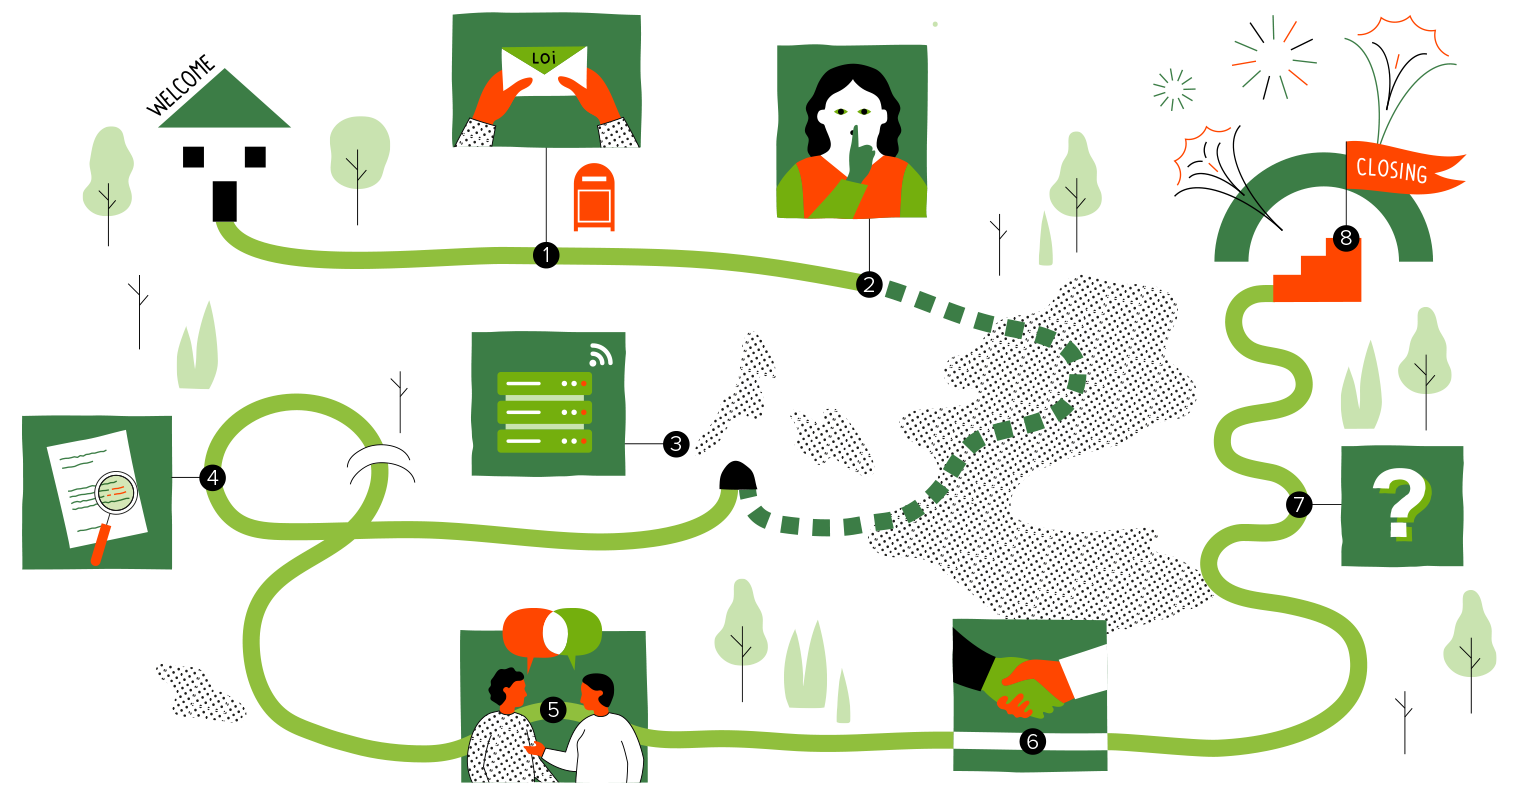
1. The letter of intent
The letter of intent is a document that specifies the intentions of its author, most often the buyer, regarding the planned acquisition/sale, and in particular the provisional price at which the author of the letter of intent is, subject to better information, willing to carry out the acquisition/sale and the projected timeline of the operations. The letter of intent is most often countersigned for agreement by its recipient.
The letter of intent is an important document insofar as it sets the guidelines for the acquisition process and often the main elements of the transaction, including the pricing basis.
You will find more information on the letter of intent, its function, content, and nature, in the section of this site related to acquisition documents.
2. The non-disclosure agreement
In an acquisition process, the parties are required to exchange sensitive and confidential information. This is particularly true for the seller, who must provide the potential buyer with information about the target, even though there is no certainty that the sale of the company will be completed. These details are even more sensitive when the potential buyer is a competitor of the target.
Moreover, the seller does not necessarily wish to disclose to employees, suppliers, or clients that they are negotiating the sale of the target.
It is therefore important, especially for the seller, to ensure that the information provided is not used in a way that could be detrimental to the target and that the sale process itself is conducted with full confidentiality. This is the purpose and objective of the confidentiality agreement.
You will find more information on the confidentiality agreement in the section related to acquisition documents.
3. The establishment of the data room
The seller is required to set up a data room. In the past, the data room referred to the physical room that the prospective buyer and his advisors could access, containing documents related to the target company. By extension, the term data room also referred to the collection of documents made available to the prospective buyer.
Today, the data room is generally digital. Various service providers offer digital data room hosting services. Since the physical room containing the documents is no longer used, the term “data room” now refers exclusively to the documents made available to the prospective buyer.
The data room is either prepared on the seller’s initiative or by the seller based on a list of documents or questions provided by the prospective buyer.
4. Due diligence
Due diligence refers to the investigations conducted by the prospective buyer prior to the execution of the share purchase agreement, aimed at gaining a deeper understanding of the target company. These investigations can cover various areas: due diligence may be financial, tax-related, environmental, legal, etc…
Due diligence, legal due diligence in particular, involves the prospective buyer’s review of the documents of the data room.
In most cases, the prospective buyer and its advisors do not limit themselves to reviewing the documents the seller has placed in the data room; they also request additional documents they consider to be missing from the data room and ask questions that arise from their examination of the documents.
Most platforms that host a data room include a question-and-answer feature, through which the prospective buyer submits their inquiries, and the seller provides responses. These exchanges themselves will become part of the data room.
Due diligence is often an essential stage of the acquisition process. Here’s why.
1) Due diligence allows the prospective buyer either to confirm their intention to proceed with the acquisition or to terminate the acquisition process.
The primary function of due diligence is to either confirm the prospective buyer’s desire to complete the transaction or, conversely, lead the prospective buyer to put an end to the acquisition process. Due diligence may indeed reveal either that the target company generally lacks attractiveness compared to the prospective buyer’s expectations, or specific issues that do not appear to have a satisfactory resolution for the prospective buyer.
2) Due diligence – or more specifically, the data room – may serve as exceptions to the seller’s representations.
The seller is required, in the share purchase agreement, to make representations concerning either the transferred shares or the target company. It is often stipulated in the share purchase agreement that the information contained in the data room constitutes exceptions to the seller’s representations. This means that the buyer is not entitled to invoke the seller’s warranty, outlined in the share purchase agreement, if a representation made by the seller is inaccurate but that this inaccuracy was disclosed to the buyer as part of the data room.
3) Due diligence may guide the drafting of the share purchase agreement.
Due diligence may guide the drafting of the share purchase agreement in several ways. For instance, it may enable the buyer to: (i) more precisely determine the price they are willing to pay for the shares, (ii) identify issues perceived as problematic and establish their resolution as conditions precedent, and (iii) identify issues perceived as problematic and convert them into specific indemnities.
5. The negotiation and execution of the share purchase agreement
With the completion of due diligence, the potential buyer has gained a more in-depth understanding of the target. They are therefore able to negotiate the share purchase agreement and, if applicable, any accompanying agreements with full knowledge of the facts.
In practice, the initial draft of the agreement is prepared by the advisors of one of the parties, most often the buyer. This draft is then exchanged between the advisors of both parties, who attempt—if necessary, during meetings with the parties themselves—to reconcile the viewpoints of their clients, whose interests may diverge.
The goal is to finalize the text of the share purchase agreement and all other legal documents binding the parties, such as the service agreement under which the seller will provide assistance to the buyer after the acquisition, the lease agreement between the target and the seller if the real estate is not included in the sale, etc.
6. The Share Purchase Agreement
This is the main document, the contract for the sale of shares. It is often a lengthy document and can be quite complex for those unfamiliar with the subject.
The complexity—a certain degree of complexity—is necessary because a company is a complex entity, holding rights and obligations, for which the buyer must obtain certain guarantees whose scope must be carefully defined. Additionally, the transaction is often significant for the parties, both financially and emotionally.
7. The fulfillment of conditions precedent or the waiver of conditions precedent
The condition precedent, that can be inserted in the share purchase agreement, is a future and uncertain event, the fulfilment of which gives rise to the seller’s obligation to sell the shares and the buyer’s obligation to buy them. The most classic example of a condition precedent – in this context – is the buyer obtaining bank financing.
After the signing of the share purchase agreement, a period may begin during which the conditions precedent must be fulfilled -—if applicable, as there is not always a condition precedent.
The parties are obligated to assist in fulfilling the conditions precedent, to the extent that their fulfillment depends on them. For example, if the buyer has completed the transaction subject to the condition precedent of obtaining bank finance, he is obliged to take the necessary steps to obtain this finance.
Article 5.144, paragraph 1 of the Civil Code sanctions a party that wrongfully prevents the fulfillment of a condition precedent. It provides that: “When one party wrongfully prevents the fulfillment of the condition, the other party may deem it fulfilled.“
The share purchase agreement may also take full effect in the event of a waiver of the conditions precedent. This waiver is addressed in Article 5.145 of the Civil Code, which provides that: “A party may waive a condition stipulated for its exclusive benefit, as long as the condition remains pending.“.
In light of this provision, it is advisable to specify in the share purchase agreement who benefits from the conditions precedent and the timeframe within which they may waive them.
8. The closing
The closing is the completion of the sale of shares, meaning the transfer of ownership of the shares, which are the subject of the sale, from the seller to the buyer.
For registered shares, the transfer is recorded in the company’s share register alongside which the seller and buyer affix their signatures.
By extension, the closing refers to the meeting between the parties during which the sale of the shares is completed.
The closing, understood as the completion of the sale of shares, can occur at the time of the signing of the share purchase agreement. Alternatively, the closing may take place after the signing of the share purchase agreement.
This may be justified by the buyer’s wish to remain the owner (and benefit from the company’s results) for longer, or by the time needed to finance the acquisition, etc. If the share purchase agreement contains conditions precedent, the closing necessarily occurs after the signing of the share purchase agreement.
Here are the most common transactions that occur at closing:
1) The share transfer is registered in the company’s share register.
2) The buyer pays the price for the shares or a substantial part of it.
Ownership of the shares is generally transferred in return for payment of the price or a specified fraction thereof. The seller does not want to sell his shares without receiving the consideration!
3) The company’s director(s) resign and (a) new director(s) are appointed.
The arrival of a new shareholder, especially a majority one, often leads to the resignation of the directors of the target company and the appointment of one or more new directors. An extraordinary general meeting is held for this purpose, potentially in the form of a written resolution.
4) Provisional discharge is granted to the resigning director(s).
The seller often requests that a clause be included in the share purchase agreement, stipulating that provisional discharge will be granted to the resigning directors at an extraordinary general meeting held during the closing. With this clause, the seller wants to prevent the target company from being able to call into question the liability of ‘its’ directors after the acquisition.
5) Collateral agreements are executed.
The closing may present an opportunity to sign collateral agreements. These could be service agreements with new managers or managers who were already in the company before the acquisition. The buyer is often looking for assistance, whether temporary or longer-term, from managers who know the business well. Collateral agreements may also take the form of a lease, where the seller retains ownership of the premises where the business operates.
When these agreements are executed between the seller and the buyer and/or their related parties, their draft is often appended to the share purchase agreement.
Post-closing formalities
The operations that take place during the closing, particularly the resignation of directors and the appointment of new directors, often require administrative formalities: publication in the Belgian Official Gazette, changes to banking powers, etc. These formalities take place after closing.